The quickest way to wreck your student budget isn’t tuition. It’s the slow leak. A dinner here. A concert there. A new phone because everyone else upgraded. A spring break trip you “can’t miss.” None of those things look like borrowing in the moment. They look like living. But when your checking account hits zero and your meal plan is gone, the gap gets filled with a credit card, a parent loan, or another chunk of student debt. That’s how extra borrowing happens: not through one dramatic decision, but through a hundred small ones that feel normal because everyone around you is making them.
The first move is to separate “broke” from “temporarily out of cash.” Broke means no money and no plan. Temporarily out of cash means you spent what you had and now need to adjust. If you’re in school and borrowing for living expenses, every dollar you spend beyond your plan is a future dollar with interest attached. That doesn’t mean you can never have fun. It means your fun has to fit inside a number. Pick a weekly spending amount for the stuff that isn’t rent, groceries, books, or transportation. Call it your sanity money. When it’s gone, it’s gone. No borrowing to refill it. This one rule prevents more extra debt than any budgeting app.
Next, watch the three big categories where students accidentally borrow: food, social life, and subscriptions. Food delivery is a debt starter kit. The fees, tip, and markup can turn a fifteen-dollar meal into thirty. If you’re already borrowing for school, paying thirty dollars for cold fries is a bad trade. Keep easy food at home: rice, eggs, frozen vegetables, peanut butter, tortillas, canned beans, fruit. Not glamorous, but it keeps you from putting a burrito on a credit card. Social life is harder because saying no feels like missing out. You can say “not this week” or suggest a cheaper plan. Host a movie night. Go for a walk. Cook together. Meet for coffee instead of dinner. Real friends won’t care. The ones who do aren’t your real friends.
Subscriptions are the silent borrow. Ten dollars here, fifteen there, and suddenly you’re paying sixty or eighty dollars a month for things you forgot you had. Go through your bank statement and cancel what you don’t use weekly. Share family plans where allowed. Rotate streaming services instead of paying for all of them. If you need one for school, keep it. Most are optional. The goal is not to punish yourself. It’s to stop paying for yesterday’s good intention with tomorrow’s borrowed money.
Housing is the other big leak. It’s tempting to sign a lease that stretches your budget because it has a pool, a gym, or a roommate you like. But rent doesn’t care about your Instagram. If the cheapest safe option saves you two hundred dollars a month, that’s two thousand four hundred dollars a year you don’t have to borrow. The same goes for cars. A reliable used car with a payment you can handle beats a new one that keeps you stressed. You are not trying to win a lifestyle contest. You are trying to graduate with as little debt as possible.
You also need a buffer. Extra borrowing often happens because one unexpected expense hits and you have no cash. A parking ticket. A broken laptop. A medical copay. Try to keep a small emergency fund, five hundred dollars, in a separate account. It won’t cover everything, but it can keep you from reaching for a credit card. Build it slowly. Ten dollars a week. Twenty when you can. The amount matters less than the habit.
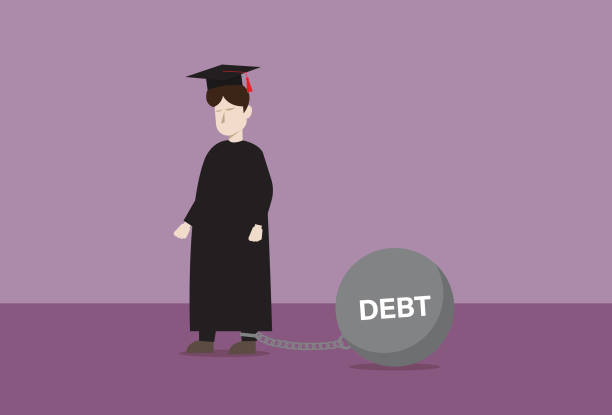
Finally, get comfortable with the word “no.” No to the trip you can’t afford. No to the dinner that will overdraft you. No to the upgrade you don’t need. No to borrowing more just to keep up. This isn’t about deprivation. It’s about control. Every time you avoid an unnecessary loan, you’re buying yourself freedom later. You’re lowering your future payment. You’re giving your future self room to breathe, save, and take a risk that isn’t about survival. Student debt is heavy enough. Don’t add to it just because everyone else is spending like the bill never comes. The bill comes. Your job is to make sure it’s smaller.